See 2026 Pennsylvania hotshot insurance costs from $7.5K–$12K/year, key coverages, FMCSA vs. intrastate requirements, and ways to save.
Hotshot truck insurance Pennsylvania pricing usually lands around $7,500–$12,000 per year in 2026 for a typical package (often $1M auto liability + $100K cargo + physical damage), with new authorities commonly higher and leased-on setups often lower.
If you want broader Pennsylvania benchmarks across truck types, start with commercial truck insurance cost in Pennsylvania and then come back to this hotshot-specific breakdown.
👉 Ready to save on your hot shot truck insurance?
Watch the video below for a quick overview of hot shot insurance rules, how much it costs, and practical ways to save. Or give us a call: (704) 290-3630
Table of Contents
Reading time: 9 minutes
- Hotshot truck insurance Pennsylvania cost estimates (2026)
- Key takeaways
- What counts as “hotshot trucking” in Pennsylvania?
- Hotshot truck insurance Pennsylvania coverage checklist
- Hotshot truck insurance Pennsylvania requirements: interstate (FMCSA) vs intrastate
- What affects hotshot insurance cost in Pennsylvania (and how to lower it)
- Next steps: get the right PA hotshot coverage (without overpaying)
- Frequently Asked Questions
- Conclusion
Hotshot truck insurance Pennsylvania cost estimates (2026)
Hotshot truck insurance in Pennsylvania typically costs $7,500–$12,000 per year in 2026 for many owner-operators when priced as $1,000,000 auto liability + ~$100,000 motor truck cargo + physical damage on the truck and trailer.
Those numbers move fast with new authority, cargo type, lanes, and driving history, so use this as a reality check—not a promised rate.
| Hotshot scenario (PA) | Low estimate (annual) | High estimate (annual) |
|---|---|---|
| Established authority (12+ months) | $7,500 | $10,200 |
| New authority (0–12 months) | $10,200 | $11,800 |
| Leased-on to a motor carrier | $4,000 | $8,500 |
| Higher-risk freight / tighter lanes | $9,500 | $14,000 |
Assumptions (typical): $1M auto liability, ~$100K motor truck cargo, plus physical damage on truck/trailer. Your exact premium depends on radius, MVR/PSP, cargo, equipment value, and prior insurance history.
Key takeaways
Most Pennsylvania hotshot owner-operators buying liability + cargo + physical damage land around $7,500–$12,000/year in 2026, with new authority (0–12 months) typically priced higher.
- Broker reality: Many brokers expect $1,000,000 CSL liability and often $100,000+ cargo even if legal minimums are lower.
- Compliance isn’t one-size-fits-all: Your filings and rules change based on interstate (FMCSA) vs intrastate-only.
- Biggest controllables: No lapses, clean MVR, honest radius, and deductibles you can actually pay.
What counts as “hotshot trucking” in Pennsylvania?
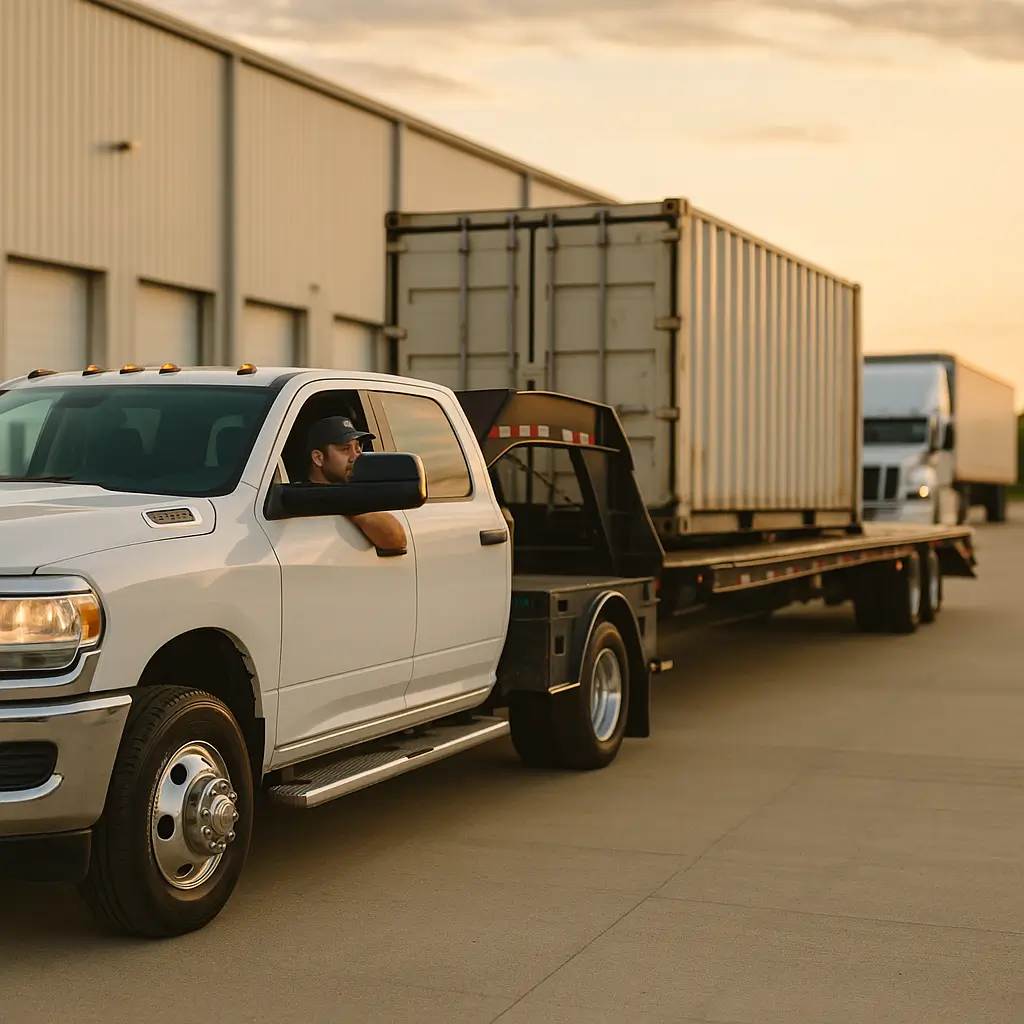
Hotshot trucking in Pennsylvania usually means a 1-ton dually pickup pulling a gooseneck/flatbed (often 30–40 feet) to haul for-hire, time-sensitive loads—often booked through brokers.
Insurers don’t rate this like “a pickup with a trailer” because the exposure is commercial: more miles, tighter schedules, more loading docks, and higher claim frequency.
How insurers typically rate hotshot setups
- Truck class: Ram 3500 / Ford F-350 / Silverado 3500-type duallys
- Trailer type: gooseneck flatbed, deckover, and some small step-decks
- Freight: equipment, palletized freight, construction materials, auto parts, expedited loads
Details that change your classification (and your price)
- For-hire vs private carriage: hauling your own materials usually prices differently than brokered freight.
- Intrastate-only vs interstate: affects filings and how underwriters view your lanes.
- Cargo type/value: higher value and certain commodities often drive higher rates and tighter exclusions.
If you want the big-picture view of how policies are structured, start with commercial truck insurance.
Hotshot truck insurance Pennsylvania coverage checklist
A practical hotshot insurance package in Pennsylvania usually includes primary auto liability, motor truck cargo, and physical damage, with add-ons like general liability or occupational accident based on how and where you haul.
Think in layers: what’s required to operate, what’s required to book loads, and what protects your equipment and cash flow.
Primary auto liability (the must-have)
Primary auto liability pays for injuries and property damage you cause to others, and it’s the first coverage brokers verify on your COI.
- Common broker expectation: $1,000,000 CSL (combined single limit)
- Who usually needs it: anyone hauling for-hire under their own authority
Motor truck cargo (what brokers will ask for)
Motor truck cargo covers the freight you’re hauling if it’s damaged, stolen, or lost due to a covered claim, and many brokers won’t load you without it.
- Common starting point: $100,000 cargo (higher for certain freight)
- Watch-outs: exclusions like unattended vehicle, improper securement, and commodity carve-outs
Physical damage (truck + trailer protection)
Physical damage (collision + comprehensive) protects your truck and trailer, and most financed equipment requires it.
- Typical claim examples: deer strikes, winter slides, theft, vandalism
- Cost lever: deductible selection should match your real emergency cash reserves
Common add-ons (often worth it)
| Coverage | When you typically need it |
|---|---|
| General liability | Job sites, facility requirements, and non-auto claims (slip-and-fall type exposure) |
| Non-trucking liability / bobtail | Often used when leased-on or when you’re not under dispatch (depends on lease language) |
| Occupational accident | If you don’t have workers’ comp and want injury protection for you (and sometimes your passenger) |
| Trailer interchange | If you pull trailers you don’t own under an interchange agreement |
Pro tip (cost control): A lot of premium pain comes from avoidable errors—wrong radius, mismatched named insured, coverage gaps, or buying limits that don’t match your freight—so review common insurance mistakes that raise premiums before you bind.
Hotshot truck insurance Pennsylvania requirements: interstate (FMCSA) vs intrastate
FMCSA requires for-hire interstate motor carriers hauling non-hazardous property with a GVWR of 10,001 pounds or more to carry at least $750,000 in public liability coverage, but many brokers and shippers commonly require $1,000,000 to tender loads.
If you run interstate: FMCSA authority + federal insurance filings
If you cross state lines (even occasionally), you’re typically operating under FMCSA rules and will need the correct authority and insurance filings to keep that authority active.
- Plain-English meaning of “filings”: your insurer electronically files proof of required coverage with FMCSA.
- Why lapses hurt: if a policy cancels, filings can be withdrawn, your authority can be impacted, and brokers may drop you fast.
FMCSA’s insurance filing requirements overview: FMCSA insurance filing requirements page
For a practical breakdown of how insurance ties into compliance checks, see FMCSA compliance requirements for DOT insurance records.
If you run intrastate only: you still may have Pennsylvania-specific steps
Intrastate operations stay inside Pennsylvania, which can change your regulator and filings, but it usually does not change what brokers require to book decent freight.
- Reality check: plenty of intrastate-only hotshot operators still carry $1M liability and cargo limits because the freight market demands it.
- What changes: your state-level registrations/permits and any required proof-of-insurance process.
PA PUC filings (Form E / Form H): what to know (without the fluff)
Some intrastate for-hire operations involve state-level proof-of-insurance filings (often referred to as Form E / Form H), and whether they apply depends on how your operation is regulated.
Step-by-step (practical checklist):
- Confirm your compliance path: intrastate-only vs interstate; for-hire vs private.
- Match the named insured: LLC vs DBA mismatches can cause filing rejections and delays.
- Pick limits that match your freight: common starting point is $1M liability + cargo sized to your loads.
- Verify acceptance: have your agent confirm filings are submitted and accepted before you haul.
- Avoid cancellations: withdrawn filings can shut down your ability to haul broker freight overnight.
Common delay problems: policy effective date doesn’t match your start date, wrong entity name/address, or late payments triggering cancellation notices that brokers can see.
What affects hotshot insurance cost in Pennsylvania (and how to lower it)
Hotshot insurance cost in Pennsylvania is driven most by authority age, driver history (MVR/PSP), radius/mileage, cargo, and equipment value, with metro exposure (Philadelphia/Pittsburgh) and winter weather often pushing rates higher.
Insurance is also a major cost pressure for carriers; ATRI’s 2026 research on 2021–2024 fleet data found commercial auto liability premiums rose 18.6% to 10.2 cents per mile: ATRI research on rising insurance costs
Pennsylvania-specific pricing pressure points
- Metro congestion: more stop-and-go exposure can increase claim frequency.
- Winter weather + grades: higher collision and comprehensive loss potential.
- Northeast repair costs: parts and labor trends hit physical damage pricing.
Underwriting factors that swing your quote the most
- New authority (0–12 months): commonly surcharged because there’s limited operating history.
- MVR/PSP: speeding, following too close, and preventable accidents are big pricing drivers.
- Radius + annual mileage: local vs regional vs multi-state exposure changes frequency.
- Cargo type + limit: higher-value loads often require higher cargo limits and tighter terms.
- Truck/trailer value + deductible + garaging ZIP: affects physical damage severity.
- Prior insurance history: lapses are expensive and can shrink your carrier options.
If you want a deeper explanation of what underwriters actually rate, see what affects the cost of truck insurance.
Savings checklist (moves that actually work)
- Don’t lapse: a lapse can raise premiums more than a higher deductible ever saves.
- Set an honest radius: don’t buy 1,000-mile rating if you run 300 and can prove it.
- Pick realistic deductibles: if your emergency fund is $2,500, a $10,000 deductible is a plan, not protection.
- Document safety: dashcams and written procedures can help when claims get disputed.
- Shop at renewal: after 12 clean months, re-marketing can bring better terms.
Want to see more ways hotshot operators lower their premiums? Watch LogRock’s video on trucking insurance savings strategies for hotshots.
Sample 2026 quote scenarios (realistic PA hotshot math)
Scenario A — New authority (higher range): Dually + 40’ gooseneck, regional PA/OH/NJ/MD, $1M liability, $100K cargo, physical damage. Typical result: closer to the top of the range due to new authority + regional exposure.
Scenario B — Established authority (lower range): 2+ years in business, clean MVR, same limits, tighter radius. Typical result: closer to the lower end because the risk looks predictable.
Scenario C — Leased-on (different spend, different risk): Motor carrier provides primary liability; you buy bobtail/non-trucking + physical damage + occ/acc. Typical result: lower total premium, but you must understand what’s covered under dispatch vs off duty.
CDL question (hotshot reality check)
CDL requirements are based on weight ratings and configuration, while insurance eligibility is mostly priced on experience, MVR/PSP, lanes, and equipment exposure—so you can sometimes get hotshot insurance without a CDL, but you shouldn’t guess on the legal requirement.
For a closer look at CDL rules for hotshot setups, watch LogRock’s video on hot shot CDL requirements.
Next steps: get the right PA hotshot coverage (without overpaying)
The best hotshot insurance plan in Pennsylvania is the one that matches your freight requirements and keeps your filings clean, because one avoidable lapse or missing limit can stop you from booking loads the same day.
When you’re ready to shop, have this ready: driver info, VINs (truck + trailer), garaging ZIP, radius, cargo/value, authority status (new vs established), and prior insurance history.
Related reading (build your quote like a business owner)
Frequently Asked Questions
Most hotshot truckers need primary auto liability, and brokered freight commonly requires motor truck cargo at $100,000+, with physical damage added to protect (or satisfy financing on) the truck and trailer. Many brokers also expect $1,000,000 CSL liability as a practical minimum to book loads. Common add-ons include general liability (job sites), bobtail/non-trucking liability (often leased-on, depending on the lease), and occupational accident if you don’t have workers’ comp. Your freight type and lanes should drive the final limits and endorsements.
Hotshot trucking insurance in Pennsylvania commonly runs about $7,500–$12,000 per year in 2026 for a typical package (often $1M liability + ~$100K cargo + physical damage), with new authority (0–12 months) often priced higher. Leased-on operators can land lower because the motor carrier may provide primary liability, but they still need the right bobtail/non-trucking, physical damage, and optional coverages. For state benchmarking across trucking operations, see commercial truck insurance cost in Pennsylvania.
You do not always need a CDL to buy hotshot trucking insurance, because insurers mainly price based on driving history (MVR/PSP), experience, lanes, and equipment—not CDL status alone. CDL legality is a separate issue that depends on your truck/trailer ratings and configuration (combined weight rating and how you operate), and a DOT stop will enforce the legal requirement even if you’re insured. Some insurance carriers do prefer CDL drivers for certain setups and may price more favorably when CDL experience is verifiable, but that varies by company and risk appetite.
Hotshot insurance quotes vary widely because each insurer applies different underwriting rules to new authorities, pickup/gooseneck operations, radius, cargo type, driver history, and equipment values. One company may heavily surcharge a 0–12 month authority, while another may simply decline it, which changes the price range you see. Physical damage pricing can also swing based on truck/trailer value, deductible, and garaging ZIP. For general background on commercial auto pricing factors, NAIC’s commercial vehicle material is a helpful reference: https://content.naic.org/sites/default/files/publication-cml-mv-commercial-vehicle.pdf.
Hotshot insurance quotes can often be issued same-day if you provide complete details (driver info, MVR, VINs, garaging ZIP, radius, cargo, and prior insurance), but FMCSA filings and authority activation timing depends on your registration status and whether you’re a new authority. If you run interstate, your insurer must submit the required electronic filings, and any mismatch in your business name (LLC vs DBA) or effective dates can slow approval. To reduce delays, follow how to prepare for the FMCSA authority application and confirm filings are accepted before booking loads.
For-hire property carriers that operate only inside Pennsylvania file proof of insurance with the Pennsylvania PUC, using Form E (liability) and Form H (cargo) submitted electronically by the insurer. According to the PUC’s motor carrier insurance page, the minimum liability is $300,000 per accident for vehicles under 10,000 lbs GVWR and $750,000 for heavier vehicles, with a $5,000 cargo minimum. Brokers usually still ask for $1,000,000 liability and $100,000 cargo, so confirm your GVWR and regulator with your agent. For more detail, see commercial truck insurance in Pennsylvania: minimums and filings.
Yes, but expect fewer carrier options and higher pricing during the first 12 months. Some insurers surcharge new authorities while others decline them outright, so your quote depends heavily on your MVR/PSP, experience, equipment, and lanes. A clean driving record, an honest radius, and complete paperwork on day one all help. Have your authority status, truck and trailer VINs, garaging ZIP, cargo details, and prior insurance history ready when you request quotes.
Dividing the typical $7,500–$12,000 annual range by 12 puts many Pennsylvania hotshot owner-operators at roughly $625–$1,000 per month for liability, cargo, and physical damage. Your actual payment depends on authority age, MVR/PSP, radius, cargo, equipment value, and the down payment your insurer requires. Leased-on operators may pay less, while higher-risk freight and tighter lanes can cost more.
A cancelled policy can lead to your insurer withdrawing your filings. For interstate carriers that can put your FMCSA authority at risk, and brokers may stop tendering loads quickly. A lapse can also raise future premiums and shrink your carrier options. If you can’t make a payment, contact your agent before the cancellation date, and review what motor carrier filings must stay active to keep your authority in good standing.
Conclusion: Build a PA hotshot policy that matches your loads and keeps your filings clean
Hotshot trucking is a thin-margin business, so your insurance should be built around the freight you actually haul and the lanes you actually run. Once you’ve got clean operations and no lapses, pricing options usually improve at renewal—especially after the first 12 months.
Key Takeaways:
- Plan around a realistic 2026 range of $7,500–$12,000/year for many PA hotshot owner-operators buying liability + cargo + physical damage.
- Use broker requirements as your baseline: $1M liability and often $100K+ cargo to access better loads.
- Lock down compliance early—especially for interstate operations—so filings don’t delay your start date.
If you’re trying to price a hotshot truck and gooseneck setup in Pennsylvania, or confirm which filings your authority needs, LogRock can help you review your operation, coverage needs, and available options. Talk to our team to ask questions, identify possible gaps, and request a quote based on your business.
Speak with LogRock and request a quote.