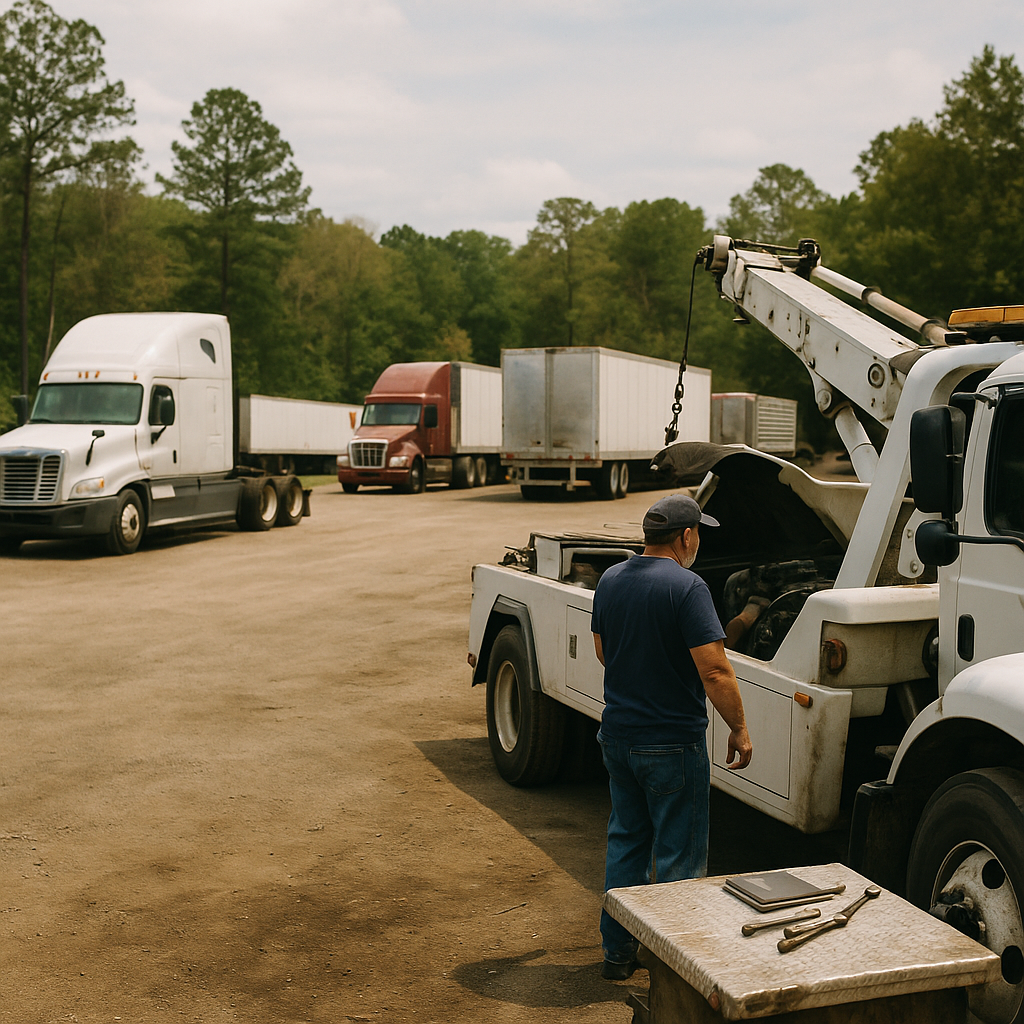
If you’re shopping for tow truck insurance South Carolina operators actually need, the first thing to know is this: a tow truck usually needs commercial coverage built for towing work, not a personal auto policy with business use scribbled in. The right setup depends on what you tow, how you operate, and whether your work stays intrastate or crosses state lines.
What South Carolina Tow Truck Insurance Covers#
South Carolina tow truck insurance is commercial insurance built around towing risks: damage you cause on the road, damage to your truck, damage to a vehicle you’re towing, and damage to vehicles stored in your care. Most tow operators need more than basic liability because towing creates exposures a normal truck policy often doesn’t cover.
Tow truck insurance starts with auto liability, which pays when your truck causes bodily injury or property damage to others in a covered accident. If you’re operating as a business, that’s the foundation of the policy, but it’s rarely the whole picture.
Physical damage pays for damage to your own tow truck. In trucking, that usually means collision, which covers damage from a crash or rollover, and comprehensive, which covers things like theft, vandalism, fire, or weather losses.
On-hook towing coverage pays for damage to a customer’s vehicle while it’s hooked up to your truck and being towed. This is one of the biggest places owner-operators get tripped up, because a tow truck policy does not automatically mean the car on the hook is covered.
Garagekeepers legal liability covers customer vehicles kept at your lot, shop, or storage location when you’re legally responsible for damage. If your operation stores cars overnight, after impounds, or while waiting on pickup, this matters fast.
Tow operators may also need protection for tools, chains, dollies, winches, and similar items. Depending on the policy structure, that can fall under equipment protection or related inland marine-style coverage rather than standard truck damage coverage.
Non-trucking liability covers a leased truck only when it’s being used for non-business driving, not while hauling or doing paid work. Most dedicated towing businesses don’t buy it as a substitute for commercial liability, and it’s often misunderstood.
What counts as essential versus optional depends on your operation:
- Roadside-only towing versus recovery work
- Storage lot exposure versus no stored vehicles
- Owner-operator versus small fleet
- Local intrastate work versus interstate movement
A cheap-looking policy can leave out the exact thing that makes a tow truck a tow truck.
If you’re not sure which towing exposures your policy actually covers,
Tow Truck Insurance vs Personal Auto Insurance#
A tow truck used for towing work usually needs commercial insurance because personal auto coverage is written for personal driving, not for-for hire roadside service, recovery, or vehicle transport. Even a single owner-operated wrecker can fall outside a personal policy once it starts generating business income.
Personal auto policies usually draw a hard line around business use. A pickup that occasionally visits a jobsite is one thing. A truck equipped and used to tow disabled vehicles for pay is something else.
That’s where operators get burned. They assume the truck is titled in their own name, so personal coverage should still work. Or they think state minimum personal auto limits carry over into commercial towing. They don’t.
The real distinction is how the truck is used:
- Personal use means private, non-business driving
- Incidental business use means light business activity that still doesn’t resemble towing for hire
- Commercial towing use means you’re being paid to tow, recover, transport, store, or service vehicles
Once you’re in commercial towing use, the policy needs to reflect that exposure. That includes the truck itself, roadside work, loading and unloading risks, and the vehicle you’re towing.
Another common mistake is assuming every tow truck policy includes on-hook or storage-related protection. It may not. One quote can include liability and physical damage only, while another also includes on-hook, garagekeepers, and equipment coverage. On paper, both may be called tow truck insurance. In real life, one leaves major gaps.
South Carolina Rules That Affect Tow Truck Coverage#
South Carolina towing rules can affect claims, liability, and which insurance protections make sense, especially if you tow from accident scenes, store vehicles, or work under police, municipal, or private-property arrangements. Federal rules can also apply when the operation fits FMCSA definitions for interstate motor carrier activity.
At the state level, towing isn’t just about driving the truck. It’s also about how vehicles are handled, stored, released, documented, and protected after the tow. That means your coverage should match the real flow of the job, not just the moment the truck is moving.
If you store vehicles, work from impound requests, or handle recoveries, your liability exposure changes. A damage claim can come from the roadway, from the hook, from the lot, or from a dispute over condition after storage. That’s why South Carolina-specific rules and claim handling standards matter. Readers should verify current state insurance and regulatory information with the South Carolina Department of Insurance.
Federal rules matter when the towing business also operates as a motor carrier in a way that triggers FMCSA oversight. Under FMCSA rules and 49 CFR Part 387 on eCFR, minimum public liability requirements depend on carrier type, vehicle weight, and commodity. For example, for-hire interstate carriers hauling general freight in vehicles over 10,001 lbs must carry at least $750,000 in public liability under 49 CFR Part 387. That does not mean all truckers or all tow operators need the same limit.
Your compliance picture can change based on:
- For-hire or private operation
- Interstate or intrastate use
- Vehicle weight
- Whether you haul disabled vehicles only or also transport other property
- Any contract requirements from police departments, shippers, auctions, or motor clubs
If you’re unsure whether federal carrier rules touch your operation, check your status through SAFER and confirm how your business is classified.
How Tow Truck Insurance Costs Are Usually Shaped#
Tow truck insurance costs vary widely because insurers price the actual operation, not just the truck itself. Monthly premium depends on things like truck value, towing radius, driver history, storage exposure, on-hook limits, equipment value, and whether you’re a single-truck owner-operator or a small fleet.
That explains why the question “How much is tow truck insurance per month?” rarely has a useful one-number answer. Two South Carolina operators can run similar wreckers and still see very different pricing because one does local roadside assistance while the other handles heavier recoveries, stores vehicles, or has tougher driver history.
The main rating factors usually include the truck’s age, value, and body type. A rollback, wheel-lift, or heavier recovery setup doesn’t create the same risk profile. Neither does a truck that stays close to home versus one that runs a larger radius or crosses state lines.
Driver history matters a lot. So does who is allowed to drive the truck. A clean, stable operation looks different to an underwriter than a business with multiple drivers, prior losses, or gaps in coverage.
Storage and custody exposures can push pricing too. If customer vehicles sit on your lot, even temporarily, that changes the risk. The same goes for the value of tools and towing equipment carried on the truck.
On-hook limits also matter. Higher limits can make sense if you regularly tow higher-value vehicles, but they can also change the quote. That’s why the right comparison isn’t just monthly premium. It’s whether each quote includes the same core protections.
When comparing quotes, line up these items side by side:
- Liability limits
- Collision and comprehensive deductibles
- On-hook coverage and limit
- Garagekeepers inclusion or exclusion
- Equipment coverage
- Named exclusions and endorsements
A lower quote may simply remove one expensive exposure from the policy. That’s not savings if the first uncovered claim comes out of your pocket.
How to Compare Tow Truck Quotes Without Buying the Wrong Policy#
The best way to compare tow truck quotes is to give each carrier or broker the same operating details, then check whether the coverages, limits, deductibles, and exclusions actually match. A cheaper quote often looks cheaper because something important was left out.
Start with a simple operating summary. Tell them what kind of towing you do, where you do it, how far you run, whether you store vehicles, what equipment rides on the truck, and whether you work under contracts or police rotation. If you do roadside assistance only, say that. If you also do recovery or impound-related work, say that too.
Then ask direct questions. Is on-hook included? Are stored vehicles covered? Is equipment covered on the truck? Are there exclusions for certain towing activities, drivers, nighttime storage, or unattended lots?
This is where quote shopping goes sideways. One policy may quote only basic commercial auto. Another may quote a towing-focused package. If you compare them on premium alone, the thinner policy wins until a claim happens.
Specialized guidance matters here because tow risks aren’t generic small-business auto risks. They involve custody of other people’s vehicles, roadside work, lot exposure, and contract language that can create coverage needs the owner-operator didn’t realize were there.
If you’re comparing policies and want help checking whether the cheaper one is missing something important,
Ways to Lower Tow Truck Insurance Costs Responsibly#
You can lower tow truck insurance costs by tightening the risk profile of the business, not by stripping out the coverages that protect your truck, equipment, or a customer’s vehicle. The safer move is to make the operation cleaner and the policy more accurate.
Start with driver quality. Clean motor vehicle records, stable driver selection, and fewer preventable losses can help over time. Secure storage, documented towing procedures, and solid lot controls can help too, especially when customer vehicles are in your care.
Accurate values matter. If the truck value is overstated, you’re paying to insure more than needed. If equipment values are guessed wrong, you can end up both overpaying and underinsured in the wrong places.
Deductibles can also change premium. A higher deductible may lower cost, but only if it’s an amount the business can actually absorb after a loss. Don’t push deductibles so high that one claim knocks out cash flow.
What not to cut too far:
- On-hook if you regularly tow customer vehicles
- Physical damage if the truck itself would be hard to replace
- Garagekeepers if you store vehicles
- Equipment protection if key towing gear rides on the truck
For owner-operators and small fleets, the smartest savings usually come from matching coverage tightly to the real operation instead of buying broad extras you don’t need or dropping core protection you do.
Get the Right Tow Truck Insurance for Your South Carolina Operation#
The right tow truck policy starts with clear information: truck details, towing type, operating radius, driver history, equipment values, and whether you store vehicles on a lot or at a yard. That gives you a quote based on the business you actually run, not a generic tow-truck label.
It also helps to know whether your work is strictly intrastate or may trigger interstate motor carrier issues, and whether any contracts require specific limits or endorsements. Small details can change the coverage structure fast.
If you’re gathering quotes, have your current policy, vehicle information, driver list, and a short description of your towing operation ready. The goal isn’t a one-size-fits-all policy. It’s a South Carolina tow truck insurance setup that fits how you really work.
FAQ#
What insurance do I need for a tow truck?
Most tow operators review commercial auto liability, physical damage, on-hook towing coverage, garagekeepers legal liability, and protection for tools or towing equipment. Auto liability covers damage or injuries you cause to others. Physical damage covers your truck. On-hook covers a customer’s vehicle while it’s being towed, and garagekeepers can matter if you store vehicles in your care. The exact mix depends on your operation, including whether you do roadside towing only, recovery work, storage, intrastate service, or interstate work. Personal auto insurance usually isn’t enough for a truck used for towing for pay.
How much is tow truck insurance per month?
Tow truck insurance per month varies by operation, so the useful answer is not a flat number. Your premium depends on truck value, towing radius, driver history, prior losses, on-hook limit, storage exposure, equipment value, and business size. A single-truck owner-operator doing local roadside work may rate very differently than a small fleet handling recoveries and storing vehicles. When you compare quotes, look beyond the monthly payment. Make sure the policies match on liability limits, deductibles, on-hook coverage, garagekeepers, and exclusions so the cheaper quote isn’t just missing protection you actually need.
Who has the cheapest tow truck insurance?
There isn’t one carrier that’s always the cheapest for every South Carolina tow operator. Pricing changes based on the risk profile of the business, including the truck, the drivers, the radius, the kind of towing, storage arrangements, and loss history. A quote that looks cheapest may also leave out on-hook, garagekeepers, or equipment protection. A better question is which quote matches your operation with the fewest coverage gaps for the premium. If you’re shopping multiple options, compare like-for-like limits and endorsements first. Your actual premium depends on your operation, cargo, radius, driving history, and other factors.
What are the towing laws in South Carolina?
South Carolina towing laws affect more than traffic compliance. They can shape liability exposure, storage practices, documentation, release procedures, and how claims are argued after a loss. If your operation tows from private property, responds to accidents, or stores vehicles, those details can change what coverage matters most, especially around on-hook and garagekeepers exposure. You should check current state requirements with the South Carolina Department of Insurance and any other relevant South Carolina agency tied to towing oversight. If your business also operates in a way that triggers interstate motor carrier rules, verify any FMCSA-related obligations too.
Does personal auto insurance ever cover a tow truck used for work?
Usually no, not once the truck is being used for commercial towing work. Personal auto insurance is designed for private driving, and many policies exclude or sharply limit business use, especially for-for hire activity. A tow truck used to earn income creates very different risks from a personal pickup or car. Even if you own the truck personally, towing disabled vehicles for pay usually requires commercial coverage written for that operation. The biggest gaps show up around liability, physical damage, and the customer’s vehicle on the hook. If the truck stores equipment or customer vehicles are kept on your lot, the gap gets wider.